News
Fortress funds lead $150 million Bluejack credit facility
The financing supports two Texas club and residential developments. Brokers assessing related businesses should separate construction funding from cash available to pay operating debt.
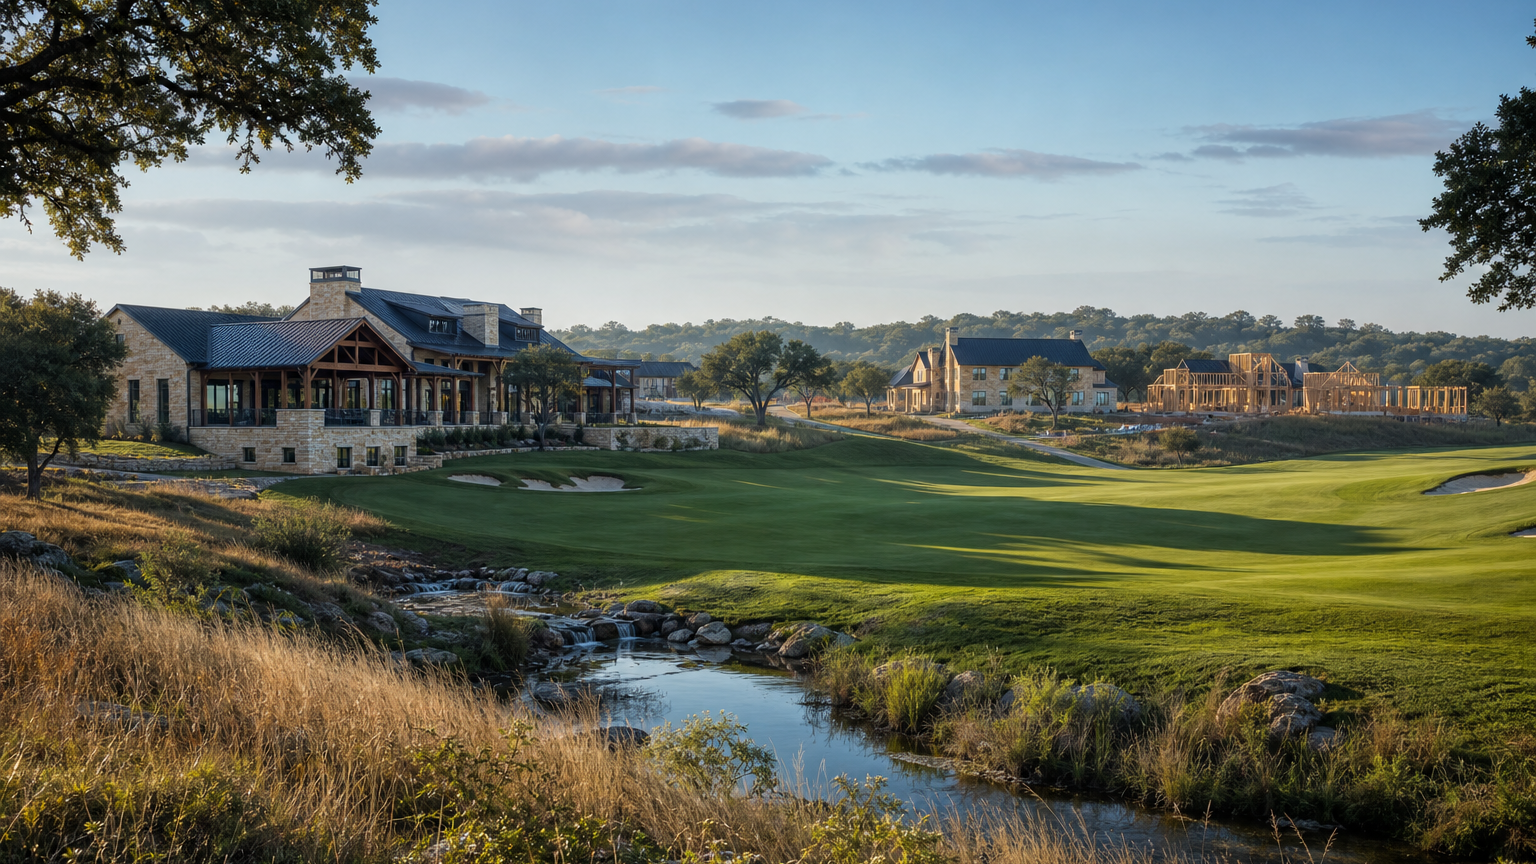
Funds managed by Fortress affiliates led a $150 million credit facility for Bluejack, the Texas private club and residential resort business. Lantern Asset Management and Fortress announced the closing on October 27. The capital supports infrastructure, amenities and development at Bluejack National in Montgomery and Bluejack Ranch in Aledo.
For brokers assessing a club operator, builder or hospitality business, the financing raises a practical question: which cash receipts can pay which obligations? A facility supporting development across a group does not establish how much cash an individual operating company can use. The answer requires the borrowing entities, permitted uses and payment arrangements, rather than the combined facility amount.
Bluejack was co-founded by Andy and Kristin Mitchell. Its courses were designed by Tiger Woods’ TGR Design, with land planning by Beau Welling Design. The announcement says the financing follows Lantern’s reorganization of Bluejack and the formation of Bluejack Management Partners. That organization combines private club operations with residential development, construction, hospitality and related businesses.
Fortress describes the financing as long-term capital. The announcement does not give a maturity, interest rate, opening draw, amortization schedule or collateral package. It also does not allocate the $150 million between the two properties. The closing confirms that a financing transaction occurred; the disclosed facility amount does not establish unrestricted cash on hand or the amount left after any closing payments.
The operating mix is visible on Bluejack Ranch’s website. It describes a 914-acre community with golf and ranch memberships, alongside residences ranging from casitas and golf cabins to estate homes. Those descriptions establish what the company markets. They do not establish membership collections, completed home sales, occupancy or project profitability.
For a comparable borrower, an underwriter should separate recurring club receipts from residential sale proceeds and construction payments. A forecast that combines them can conceal a timing problem even when its annual total looks adequate. A home sale expected later in the year cannot pay next month’s payroll unless the business has cash or committed funding available before then.
The supporting file should connect each forecast receipt to its legal entity and expected collection date. Bank statements can then test whether recorded collections reached the account available for operating payments. For membership receipts, check the applicable payment and refund terms. For residential sales, distinguish a reservation or deposit from a completed sale and confirm any restrictions on the money. These are diligence questions for similar businesses, not disclosed problems at Bluejack.
Construction costs need the same treatment. If a comparable facility releases funds against approved work, the cash forecast should reflect the actual approval and draw schedule. An approved overall budget would not, by itself, establish that cash arrives before a contractor invoice is due. The Bluejack announcement does not disclose whether its facility uses that funding structure.
Nor does the operating platform’s combined ownership establish that every subsidiary guarantees the debt or that money can move freely between properties. Brokers considering additional financing should obtain the existing loan restrictions and determine which entity would owe the new payments. A sponsor’s involvement or a prominent course designer does not establish a guarantee, pledged collateral or a commitment to cover future shortfalls.
Opinion
Test the operating company’s payment capacity
Before proposing another daily or weekly debit for a business inside a development group, build a dated cash forecast for the actual borrower. Exclude restricted funds and uncompleted sales until their conditions are met. If repayment depends on transfers from another group company, document that company’s ability and authority to make them. Otherwise, the proposed payment rests on cash the borrower may never control.
Read more on financing and borrower cash flow at plutusai.net.